Treasury yields did in one session what months of AI earnings beats couldn’t undo: they knocked the market’s swagger down a notch. The 10-year yield hit its highest level in almost two decades on Wednesday, and stocks across nearly every sector went red to match it, in one of the clearer reminders this year that the AI trade doesn’t operate in a vacuum from the rest of the economy.
The Number That Spooked Everyone
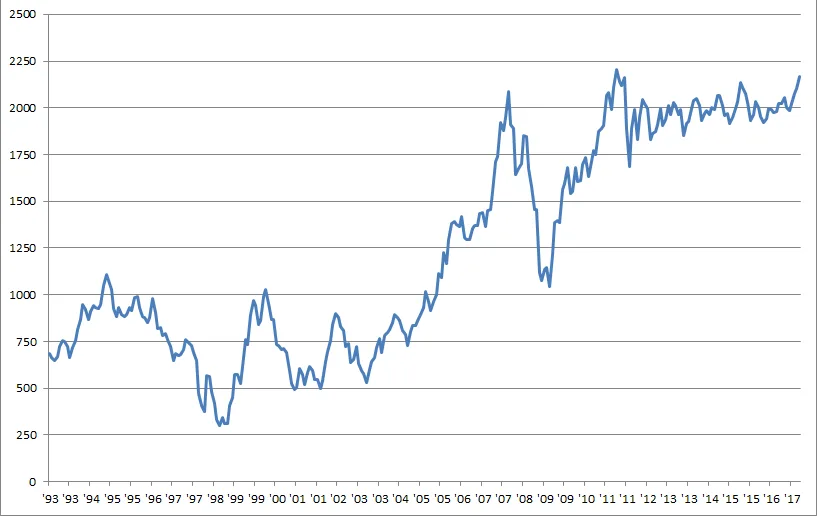
The 10-year Treasury yield climbed 11 basis points to 5.08% during Wednesday’s session, its highest mark in roughly 19 years. That’s not a small move for a single day in the bond market, and it didn’t happen in isolation — it followed a string of stronger-than-expected business activity data that gave investors fresh reason to worry the Federal Reserve’s inflation fight isn’t as close to finished as the past couple of months of market optimism had assumed.
Higher yields hit stocks through a fairly direct mechanical channel: as government bonds pay more just for sitting still, the future earnings that growth stocks and AI companies are priced on become relatively less attractive by comparison, and borrowing costs across the economy tick up right along with them. Mortgage rates, for instance, jumped to 7.12% Wednesday, their highest level in more than two years, which put visible pressure on homebuilder stocks like KB Home as the day went on.
Where the Damage Landed
By midday, the S&P 500 was down 0.75% to 7,706, the Nasdaq Composite had fallen a sharper 1.13% to 26,936, and the Dow Jones Industrial Average slipped 0.68% to 51,512. The tech-heavy Nasdaq’s larger decline reflects exactly the dynamic described above — growth and AI-adjacent names carry more of their valuation in future earnings, which makes them more sensitive to a sudden yield spike than a diversified industrial index.
Gold, often treated as the reflexive inflation hedge, actually fell too, down 1.88% to $4,283.13 — a move that runs slightly counter to the textbook playbook and suggests some of Wednesday’s selling was more about repositioning and rate-driven portfolio math than a straightforward flight to safety.
The One Sector That Went Up
Energy was the lone sector to close the session in positive territory, a detail that tracks with the broader unease driving the day: elevated oil prices were cited alongside the yield spike as one of the pressures weighing on the rest of the market, and energy stocks tend to benefit directly from exactly the kind of oil price strength that hurts everyone else’s input costs.
Cybersecurity’s Unusual Rally
The more interesting pocket of strength Wednesday came from cybersecurity names. CrowdStrike and Palo Alto Networks both rallied even as the broader tech sector sold off, with investors specifically citing the role these firms might play in AI safety and defense as a reason to keep buying. That’s a notable shift in how the market is pricing AI-adjacent risk — less which company has the best model and more which company can secure the infrastructure everyone else is building on top of. Given the same week saw Microsoft publicly disrupt an AI-powered phishing operation and OpenAI and Anthropic warn the UN Security Council about AI systems slipping beyond human control, that repricing doesn’t look like a coincidence.
The Xi Jinping Visit Looming Over Everything
Adding a geopolitical layer to an already jittery session, Chinese leader Xi Jinping’s planned visit to the United States this week is expected to touch directly on AI and trade negotiations, alongside ongoing tension in the Middle East and lingering concerns about shipping through the Strait of Hormuz. None of those threads resolved on Wednesday, and markets generally don’t like unresolved geopolitical threads sitting on the calendar — that uncertainty compounds whatever the bond market is already doing on its own.
What Traders Are Watching Next
The immediate question for the rest of the week is whether Wednesday’s yield spike holds or gets partially reversed once the specific data prints driving it get digested more fully. A yield move this size in a single session often overshoots in the short term, and bond traders will be watching upcoming inflation and employment data closely for confirmation that the underlying trend actually justifies pricing in a slower path of rate cuts from the Fed. Equity investors, meanwhile, will be watching whether the Nasdaq’s underperformance Wednesday marks the start of a broader rotation out of AI and growth names, or just a one-day gut check before the rally resumes.
What This Means
Nothing about Wednesday’s session breaks the AI-driven bull market that’s carried indexes for the better part of two years, but it’s a useful reminder that the bond market still sets the terms that stock valuations have to live within. A 10-year yield at a 19-year high is a real cost of capital, not a headline — and every AI company whose stock price depends on earnings five or ten years out just got a little more expensive to justify. Watch the next round of inflation data closely; it’ll do more to determine where the market goes from here than any single product launch this month.